Key Takeaways
|
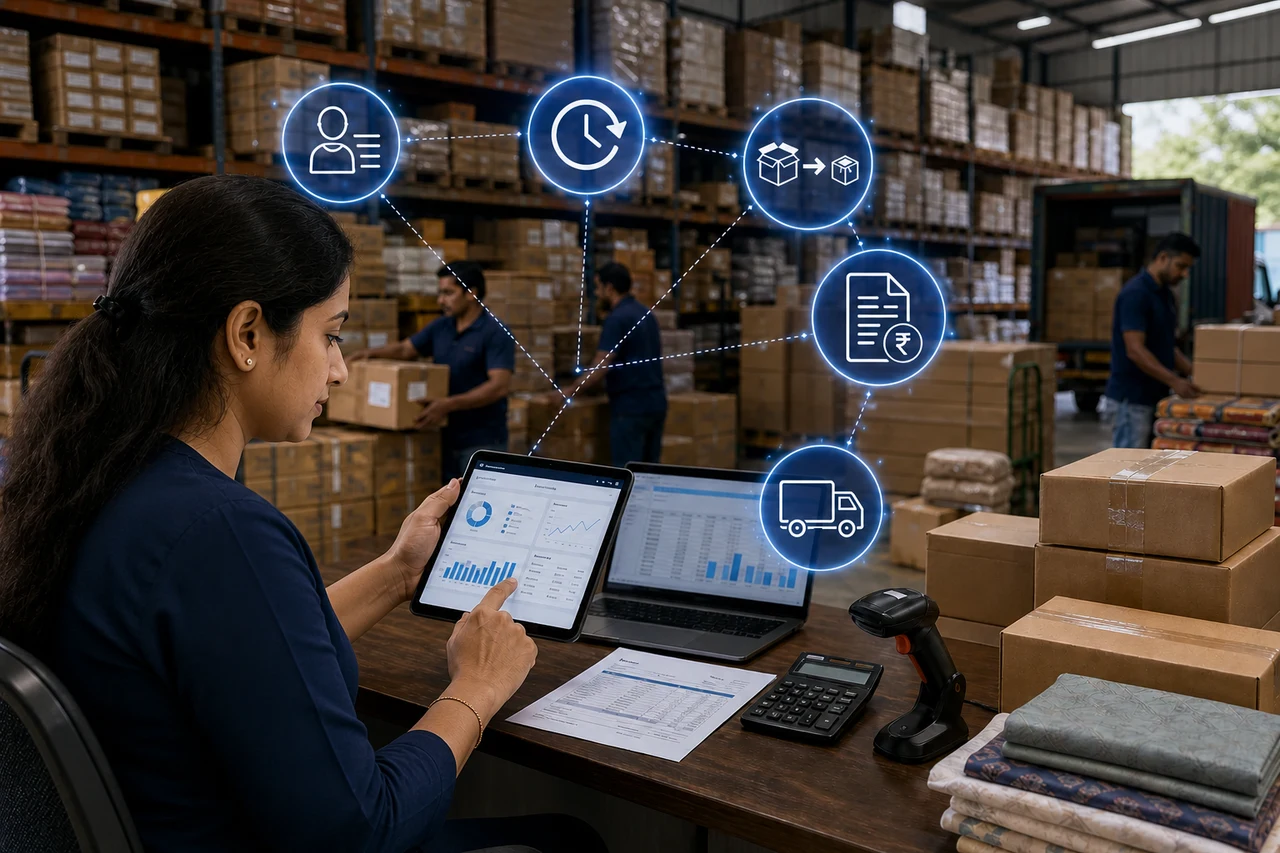
Trading and wholesale in India runs on credit and trust. A FMCG distributor in Pune supplies 200 retailers across the district, all on 30-day udhaar. A hardware wholesaler in Ahmedabad dispatches 15 consignments per day to contractors across two states, each requiring an e-way bill before the goods leave the godown. A textile trader in Surat buys fabric in metres and sells in pieces, with different pricing for different buyers at different volumes. None of these businesses have accounting needs that a retail billing app or a basic invoicing tool can serve. Their problems are different: party-wise credit management, multi-unit billing, inter-state IGST on large consignments, GSTR-2B matching against hundreds of supplier invoices, and outstanding receivables that, if not tracked daily, become bad debt.
This guide explains what accounting software for traders and wholesalers in India must do, how it differs from retail billing tools or standard accounting software, the specific GST compliance requirements that apply to trading and wholesale businesses, and how to choose the right platform for your business size and trade type in 2026.
How Trading and Wholesale Accounting Is Different from Retail and Service Accounting
Accounting software for traders must handle a set of operational and compliance requirements that neither retail POS tools nor professional services accounting platforms were designed for. The core difference: a trader’s business model is built on margin between purchase price and sale price across high volumes, on credit terms, with large B2B consignments that attract GST and e-way bill requirements at every stage.
| Dimension | Retail Shop | Service Business | Trader/Wholesaler |
|---|---|---|---|
| Primary transaction type. | B2C (consumer): mostly cash or UPI at counter. | B2B (businesses): invoices on credit terms. | B2B (retailers, contractors, businesses): large volume invoices on credit terms. |
| Invoice volume and size. | Many small invoices (Rs 100 to 5,000). Speed at counter is the priority. | Few large invoices per month. Accuracy and contract compliance are the priority. | Mix of high-volume smaller invoices (distributors) and large-value invoices (bulk traders). Both speed and accuracy matter. |
| Credit management. | Occasional udhaar for known customers. Low risk per transaction. | Project-based milestone billing. Formal credit terms with contracts. | Most sales on credit. Multiple parties, multiple credit limits, multiple outstanding balances running simultaneously. The primary cash flow risk. |
| Inventory management. | Finished goods only. One unit of measure per product usually. | Typically no inventory. Billing for time or project deliverables. | Multi-unit billing (cartons to pieces, kg to grams, bales to metres). Multi-godown stock across locations. Purchase price matters for margin calculation. |
| GST complexity. | Mostly B2C: no e-invoicing required currently. Single state GST applies. | B2B: may need e-invoicing above Rs 5 crore AATO. SAC codes for services. | B2B supply chain: e-invoicing mandatory above Rs 5 crore AATO. IGST on inter-state supply. E-way bill for most consignments. GSTR-2B matching across many suppliers. |
| Party-wise pricing. | Fixed MRP or standard pricing for all customers. | Custom project pricing per client. | Different price lists for different buyer tiers. Scheme discounts for volume. Trade discounts on specific products for specific parties. |
| Supplier management. | Fewer suppliers. Mostly cash or short-credit purchases. | Minimal purchases. Professional subscriptions or subcontractor costs. | Multiple suppliers. Purchase credit terms of 30 to 90 days. ITC on every supplier invoice. Supplier GSTR-1 must match for ITC claim. |
The Six Core Problems Accounting Software Must Solve for Traders in India
Most Indian traders and wholesalers run their business across a combination of Tally, Excel, WhatsApp, and memory. Each of the six problems below represents a place where this combination fails and where the right accounting software for traders delivers a structural fix.
Problem 1: Udhaar and Credit Management Across Multiple Parties
Udhaar is the backbone of Indian wholesale trade. Every retailer buys on credit from the distributor. Every contractor takes materials on account. The problem is not extending credit, which is commercially necessary. The problem is tracking it. When credit extended to 150 parties is managed across notebooks, WhatsApp messages, and memory, the ₹31,000 that went unrecorded against one buyer’s account in a manual system is a common outcome, not an isolated incident.
- Party-wise credit limit: each buyer has a maximum outstanding balance above which further credit supply should not be extended.
- Running ledger per party: every sale, every payment, and every return recorded automatically in that party’s account.
- Outstanding balance alert: when a buyer’s outstanding exceeds their credit limit, the software flags the next bill before it is confirmed.
- Payment reminder: automated WhatsApp or SMS reminder to parties with overdue balances without the owner having to remember to call.
- Ageing report: outstanding balances categorised by age (0 to 30 days, 31 to 60 days, 61 to 90 days, above 90 days) so overdue accounts are visible before they become bad debt.
54% of businesses experience late payments, with 33% of invoices overdue by more than one month. For an Indian wholesaler with ₹50 lakh of outstanding at any point, untracked ageing means ₹10 to 15 lakh may be in the overdue category without a visible alert.
Problem 2: Multi-Unit Billing with Automatic Conversion
An FMCG wholesaler bills in cartons but stocks in pieces. A textile trader buys fabric in metres and sells to retailers in pieces. A hardware distributor bills in boxes of 24 units but receives goods from the manufacturer in packs of 144. Every accounting software for traders in a trading or wholesale context must handle this unit conversion automatically: sell 2 cartons, stock reduces by 48 pieces. Bill in metres, purchase in kg with a conversion factor applied at the item level.
- Multiple units of measure per item (pieces, dozens, cartons, kg, litres, metres, bales) with defined conversion ratios.
- Billing in the buyer’s preferred unit while stock is maintained in a standard base unit.
- Automatic stock deduction in base unit when sale is made in any alternate unit.
- Purchase recording in supplier’s unit with automatic conversion to base unit for stock update.
Problem 3: Party-Wise Pricing and Scheme Management
A wholesaler supplying the same product to 200 retailers does not charge the same price to all of them. Large-volume buyers get a better price. Loyal customers get a scheme price. New accounts start at MRP minus a standard trade margin. Managing price lists per party, and applying the right price automatically when raising a bill for that buyer, is a core requirement of accounting software for traders that generic billing tools do not support.
- Party-wise price lists: define different selling prices per customer or customer group.
- Volume-based pricing: automatic rate change when quantity crosses a defined threshold (e.g. 10 cartons at ₹850, above 10 cartons at ₹820).
- Scheme management: quantity or value-based schemes (buy 10 get 1, 5% additional margin on scheme SKUs) tracked and reported.
- Trade discount management: flat discount percentage applied per party, automatically deducted in billing.
Problem 4: IGST on Inter-State Supply and E-Way Bill Generation
A trader supplying goods from Mumbai to buyers in Rajasthan, Gujarat, and Karnataka on the same day must apply IGST (not CGST plus SGST) on each of those invoices, because supply crosses state boundaries. For each consignment above ₹50,000, an e-way bill must be generated before the goods leave the godown. For high-volume distributors, generating an e-way bill per delivery manually through a separate portal login is not operationally viable.
- Automatic IGST vs CGST/SGST determination based on place of supply vs supplier’s state of registration.
- E-way bill auto-generation from invoice data for qualifying consignments: no separate portal login per delivery.
- E-way bill validity tracking: 1 day per 200 km for normal cargo, alerts for consignments near validity expiry during transit delays.
- Multi-GSTIN support for traders registered in multiple states.
Problem 5: GSTR-2B Reconciliation Across Many Supplier Invoices
A wholesale business buying from 40 to 80 suppliers per month generates 200 to 500 purchase invoices that must all appear in GSTR-2B for ITC to be claimed. Every invoice where the supplier’s GSTR-1 does not match is a blocked ITC. For a FMCG distributor spending ₹80 lakh on purchases per month at an average 12% GST rate, that is ₹9.6 lakh of ITC at stake each month. A 5% reconciliation failure rate represents ₹48,000 per month in permanently lost working capital.
- GSTR-2B auto-downloaded from GSTN API on the 14th of each month: no manual portal download.
- Automated reconciliation: each purchase invoice in the system matched against GSTR-2B entry from the supplier.
- Mismatch report by category: Bucket A (in GSTR-2B but not in books), Bucket B (in books but not in GSTR-2B), Bucket C (in GSTR-2B but unclaimed).
- Supplier follow-up list: specific suppliers whose invoices did not appear in GSTR-2B, with invoice details for follow-up calls.
- ITC eligible amount auto-flowing to GSTR-3B preparation: no manual calculation of claimable credit.
Problem 6: The 180-Day Supplier Payment Rule and ITC Reversal Risk
Under Section 16(2) of the CGST Act, if a registered person does not pay their supplier within 180 days of the invoice date, the ITC claimed on that purchase must be reversed, along with interest at 18% per annum. For a trader with accounts payable across 50 to 80 suppliers, some invoices inevitably approach the 180-day mark, particularly with small suppliers who accept delayed payment. Without a system tracking the age of each payable against the 180-day rule, ITC reversals are discovered at the annual audit rather than managed proactively.
- Payable ageing per supplier with days outstanding per invoice.
- 180-day ITC reversal alert: invoices approaching the 180-day deadline flagged for payment prioritisation or ITC reversal provision.
- Automatic ITC reversal entry when a payable exceeds 180 days without payment, for inclusion in GSTR-3B.
Trader and Wholesaler Types: What Each Business Needs from Accounting Software
Not every trading or wholesale business has the same profile. Here is how accounting software for traders requirements vary across the main Indian trader types.
| Trader/Wholesaler Type | Key Accounting Requirements | GST-Specific Needs |
|---|---|---|
| FMCG distributor. | High invoice volume (100 to 300 per day). Scheme and incentive tracking per buyer. Credit limit management for 100 to 300 retailers. Stock in cartons and pieces. Route-wise sales tracking. | E-invoicing for B2B sales above Rs 5 crore AATO. E-way bills on most deliveries. GSTR-2B reconciliation across 30 to 50 FMCG manufacturers. Returns and credit note management when goods returned. |
| Textile and fabric trader. | Multi-unit billing (metres, kg, pieces). Lot and shade tracking on fabric purchases. Party-wise pricing by buyer category. Both B2B wholesale and some retail supply. | GST rates vary by fabric type (5% for most fabric under GST 2.0 uniform rate). HSN chapters 52 to 55 and 61 to 63. Export billing for fabric exports (zero-rated, LUT required). IGST on inter-state supply. |
| Steel and metal trader. | Commodity trading with price fluctuation. High-value consignments. Weight-based billing (MT, kg). Credit terms of 30 to 60 days standard. | 18% GST on most steel products. E-way bill mandatory on most consignments (high value). IGST on inter-state supply to construction sites. |
| Pharma stockist/distributor. | Batch and expiry date tracking mandatory. Returns management (expired stock). Near-expiry alerts. Manufacturer-wise credit tracking. Bonus/free goods scheme management. | Pharma product GST rates (5% for most medicines, 12% for some). Strict batch-level invoice records. |
| Agricultural commodities trader. | Produce bought in quintals sold in smaller units. Moisture content and quality grade affects pricing. Mandi receipts and weighment slips as supporting documents. | Most agricultural produce is GST-exempt. Processed food may attract 5% or 18%. Careful product classification between exempt and taxable. |
| Electronics and technology distributor. | IMEI/serial number tracking. Warranty registration per unit. High value per unit: credit risk management critical. | Mobile phones at 12% GST. Most electronics at 18%. E-invoicing mandatory for most electronics distributors above threshold. |
| Automobile parts distributor. | OEM vs aftermarket parts on same invoice. Fitment guides and compatibility tracking. Warranty claim processing. | Most automobile parts at 18% GST. Credit notes for warranty replacements must link to original invoice in GSTR-1. |
GST Compliance Requirements Specific to Traders and Wholesalers in 2026
E-Invoicing Is Mandatory and Affects More Traders Than They Realise
E-invoicing (IRN generation from the IRP) is mandatory for all B2B transactions from businesses with AATO above ₹5 crore across all GSTINs under one PAN. For a FMCG distributor with a single GSTIN and ₹6 crore annual turnover, this is clear. For a trader operating under a sole proprietorship with two state registrations each below ₹3 crore but combined above ₹5 crore, the e-invoicing obligation still applies. Calculated on combined PAN-level AATO. Once the threshold is crossed in any financial year from FY 2017-18, e-invoicing applies permanently even if turnover drops subsequently.
Traders who have never filed for e-invoicing but whose combined AATO has crossed ₹5 crore in any prior year since FY 2017-18 are currently non-compliant on every B2B invoice. Their buyers cannot claim ITC on those invoices. Verify your e-invoicing status at einvoice6.gst.gov.in.
GSTR-1 Locking GSTR-3B from July 2025: Errors Cost More
From July 2025, the output tax liability declared in GSTR-1 locks into GSTR-3B and cannot be reduced. A trader who incorrectly includes a cancelled invoice in GSTR-1, or applies the wrong HSN code creating a higher-than-correct rate, cannot correct it downward in the same period’s GSTR-3B. The correction must happen via GSTR-1A in the next period. This increases the cost of billing errors for high-volume traders significantly.
IMS: Mandatory Monthly Action on Incoming Invoices
From October 2025, traders and wholesalers must review incoming supplier invoices in the GST portal’s Invoice Management System (IMS) before the 11th of each month. Invoices not actioned are auto-accepted, including wrong-amount or incorrect-GSTIN invoices. For a trader receiving 200 to 500 purchase invoices per month, this requires a systematic weekly IMS review process or an integrated accounting platform that surfaces IMS pending invoices within the normal accounts payable workflow.
The 180-Day Payment Rule and ITC Reversal
Under Section 16(2) of the CGST Act, ITC claimed on a supplier invoice must be reversed if the supplier is not paid within 180 days of the invoice date. For traders on extended credit from manufacturers (60 to 90 day terms are common), invoices from the first month of the year must be paid by around the sixth month or ITC reversal is triggered. With 18% interest on the reversed amount from the date of the original claim, the financial penalty for missing this deadline is material.
The Party Ledger System: The Heart of Trader Accounting
In Indian trading and wholesale, the party ledger is the central record of every relationship. Every customer (debtor) has a ledger showing what they owe you. Every supplier (creditor) has a ledger showing what you owe them. The accounting software for traders that handles these ledgers correctly, automatically, in real time, with ageing and alerts, is the most important operational tool a trader has.
What a Customer (Debtor) Ledger Must Show
- Every invoice raised: date, invoice number, value, GST amount.
- Every payment received: date, amount, payment mode (NEFT, RTGS, cheque, cash, UPI), and which invoices the payment was applied against.
- Every credit note issued: when goods were returned or a price adjustment was made.
- Running outstanding balance after every transaction.
- Credit limit vs current outstanding: how much more can this party buy on credit before the limit is reached.
- Ageing breakdown: total outstanding categorised by 0 to 30, 31 to 60, 61 to 90, and above-90-day buckets.
What a Supplier (Creditor) Ledger Must Show
- Every purchase invoice recorded: date, invoice number, supplier’s GSTIN, value, GST amount, ITC claimed.
- Every payment made: date, amount, payment mode, and which invoices settled.
- Every debit note raised: when goods were returned to the supplier or a rate correction was claimed.
- 180-day countdown: number of days since each unpaid invoice was raised, with alert when approaching 180.
- GSTR-2B match status per invoice: whether the supplier has filed and whether ITC is confirmed, pending, or mismatched.
The Reconciliation Between Party Ledger and GSTR-2B
The debtor and creditor ledgers in the accounting system must reconcile with the GST portal in both directions. Outward: what you billed in the accounting system must match what appeared in your buyers’ GSTR-2B (i.e. what you filed in GSTR-1). Inward: what your suppliers billed you must match what appeared in your GSTR-2B. Any gap between the ledger and the portal is either a compliance risk or a lost ITC. Integrated accounting software for traders that automates both reconciliations is the only practical way to manage this at trading volumes.
Accounting Software for Traders: Complete Feature Checklist
Use this checklist when evaluating any accounting software for traders or wholesalers. The items specific to Indian trading, including IMS, 180-day rule, e-way bill, and IGST auto-selection, are non-negotiable for any business above ₹1 crore turnover.
| Feature | Why It Matters for Traders | Priority |
|---|---|---|
| Party-wise credit limits with real-time outstanding. | Core udhaar management. Without this, credit leaks silently to every party that pushes for more goods on account. | Mandatory. |
| Receivables ageing report (0 to 30, 31 to 60, 61 to 90, 90+ days). | Identifies overdue balances before they become bad debt. 33% of invoices overdue more than one month in typical wholesale businesses. | Mandatory. |
| Payment reminders via WhatsApp. | Low-friction collection tool. Reduces the awkwardness of collection calls. Automated reminder linked to outstanding age. | Strongly recommended. |
| Multi-unit billing with auto-conversion. | FMCG, textile, hardware, agri: every commodity trade involves unit conversions. Manual conversion introduces systematic errors. | Mandatory for commodity traders. |
| Party-wise price lists. | Different buyers pay different prices. Applying a single price list to all buyers undercharges volume buyers or overcharges retail customers. | Mandatory for wholesalers with tiered pricing. |
| IGST vs CGST/SGST auto-determination. | Inter-state supply requires IGST. Wrong tax type creates GST mismatch and buyer ITC issues. Must be determined by place of supply vs supplier GSTIN state automatically. | Mandatory. |
| E-way bill auto-generation from invoice. | Most B2B consignments above Rs 50,000 require e-way bill. Manual portal generation per shipment is not viable at trading volume. | Mandatory for goods traders. |
| E-invoicing with IRP API (IRN generation). | Mandatory for AATO above Rs 5 crore. Buyers cannot claim ITC without valid IRN. Non-compliance risks penalties. | Mandatory if AATO above Rs 5 crore. |
| GSTR-2B auto-reconciliation. | 200 to 500 purchase invoices per month. Manual GSTR-2B matching is 6 to 10 hours per month. ITC loss from missed matches can be Rs 50,000+ per month. | Mandatory. |
| 180-day payable tracking with ITC reversal alert. | ITC reversal risk when suppliers not paid within 180 days. Most traders are unaware until the CA flags it at year-end. | Mandatory. |
| IMS dashboard within the platform. | Active supplier invoice management before 11th. Without this, IMS requires a separate portal login for each review session. | Mandatory from October 2025. |
| Multi-godown/multi-location stock management. | Traders with godowns in multiple locations need consolidated and location-wise stock view from one account. | Required for multi-location traders. |
| Purchase order and GRN management. | Large traders issue POs to suppliers and need to receive against those POs (Goods Receipt Notes) to validate quantities before payment. | Strongly recommended. |
| CA access with read-only role. | CA needs access to party ledgers, GST data, and financial reports without admin access to pricing or inventory settings. | Strongly recommended. |
Elixir Books for Traders and Wholesalers
Elixir Books is an integrated MSME Finance ERP that serves trading and wholesale businesses requiring full accounting, GST compliance, and inventory management from a single platform. It is the right choice for traders who have outgrown basic billing tools and need the accounting depth to manage party ledgers, GSTR-2B reconciliation, and multi-location stock without running parallel systems.
Here is what the platform provides for traders and wholesalers.
- GST-compliant billing with auto-calculated CGST/SGST or IGST based on place of supply: correct tax type applied automatically without manual selection.
- Party-wise ledgers: every customer and supplier account maintained with running balance, payment history, and outstanding ageing.
- Real-time inventory across locations: stock deducted on every sale, updated on every purchase, visible across multiple godowns.
- E-invoicing with direct IRP API integration: IRN generated at point of billing for B2B transactions in businesses above ₹5 crore AATO. Available as an add-on module.
- E-way bill auto-generation from invoice data for qualifying consignments above the threshold.
- Automated GSTR-2B reconciliation: purchase invoices matched against GSTN supplier data with Bucket A, B, C categorisation, ITC eligible amount flowing to GSTR-3B. Available as an add-on module (₹250/month).
- IMS integration: pending supplier invoices surfaced for review within the platform before the 11th: no separate portal session required.
- 180-day payable alerts: invoices approaching the 180-day mark flagged for payment prioritisation or ITC reversal provision.
- GST return preparation: GSTR-1 auto-populated from billing data, GSTR-3B pre-filled from reconciled data, CA access for filing.
- Multi-GSTIN support for traders registered in multiple states.
For a full breakdown of platform features, see the Elixir Books features page. For pricing and add-on module details, see the plans and pricing page.
For the GSTR-2B reconciliation workflow in detail, read: Avoiding Losses: Master GST Reconciliation with Elixir Books. For how integrated accounting eliminates reconciliation errors for traders, read: Cloud vs Traditional Accounting Software in India.
For related guidance, read our complete guide to integrated accounting, our guide to GST software for MSMEs, and our article on reducing reconciliation errors.
Official references: GST e-invoicing mandate and GST e-way bill portal.
Leave a Reply